Nasdaq Real-Time Stock Data: Why Pyth Matters
Overview
Pyth Network has become an approved external distributor of Nasdaq Basic, giving software and blockchain-oriented applications a new licensed channel for accessing real-time U.S. equity market information. Announced on September 22, 2026, the arrangement allows eligible customers to obtain Nasdaq Basic through Pyth’s Data Marketplace, extending Pyth beyond crypto-native price feeds and deeper into traditional financial-market infrastructure.
The development is important because Nasdaq real-time stock data is not becoming freely permissionless simply because Pyth operates blockchain-oriented data infrastructure. Nasdaq Basic remains a proprietary market-data product, and customers using it through Pyth must satisfy Nasdaq licensing and approval requirements. Pyth is therefore acting as a distribution channel rather than converting regulated market data into a public-domain oracle feed.
This distinction also explains the broader industry significance. Tokenized stocks, equity perpetuals, lending markets and other onchain financial products cannot scale solely through asset tokenization. They require reliable information about bids, offers, trades, opening prices and closing prices. As traditional securities move closer to blockchain infrastructure, licensed market data increasingly becomes part of the same transition.
The Pyth-Nasdaq relationship is therefore best understood as an infrastructure development: the data layer that supports conventional securities markets is beginning to become more compatible with software-native and onchain financial applications.
Key Takeaways
- Pyth is now an approved external distributor of Nasdaq Basic.
- Nasdaq Basic provides proprietary real-time quote and trade data for U.S. equities.
- Access through Pyth remains subject to Nasdaq licensing and approval requirements.
- The product is not the full consolidated U.S. equity tape.
- Reliable licensed market data could become critical infrastructure for tokenized stocks and equity-linked DeFi.
What Nasdaq Real-Time Stock Data Can Pyth Distribute?
What Is Nasdaq Basic?
Nasdaq Basic is a proprietary real-time U.S. equity market-data product designed to provide a lower-cost alternative to full Level 1 consolidated data for many use cases. It includes real-time quote and trade information sourced from Nasdaq’s U.S. equity venues and related trade-reporting infrastructure, while covering securities listed across major U.S. exchanges.
The product includes best bid and offer data, quote sizes, last-sale information and official opening and closing prices. It can therefore support applications that need a live view of U.S. equity prices without necessarily purchasing every element of the national consolidated data infrastructure.
This is where precision matters. Nasdaq Basic should not be described as the entire U.S. consolidated tape. It is a Nasdaq proprietary data product with broad U.S. equity coverage, but its data composition and licensing structure differ from the Securities Information Processor feeds traditionally associated with consolidated market data.
Pyth’s role is to create another approved distribution route for this information, particularly for customers building software-native or blockchain-oriented products.
What Market Information Is Included?
Nasdaq Basic is designed to deliver core information needed to understand current market conditions: actionable bid and offer prices, sizes, last-sale information and official price benchmarks. Depending on the applicable Nasdaq Basic configuration, the feed also incorporates information associated with Nasdaq U.S. venues and FINRA/Nasdaq Trade Reporting Facilities.
For an onchain financial application, these data categories serve different functions. Best bid and offer information can help establish current market value, last-sale data provides evidence of executed transactions, and official opening and closing prices can support settlement or benchmark calculations.
The data becomes especially important when a blockchain product references a traditional security but does not itself contain enough liquidity to generate a reliable independent price. In that situation, the quality of the external market-data source becomes part of the product’s risk architecture.
How Does Pyth Distribute Nasdaq Real-Time Stock Data?
Is Nasdaq Data Now Permissionless?
No. Becoming an external distributor does not make Nasdaq real-time stock data freely available to every wallet, smart contract or application without restrictions. Nasdaq retains commercial control of Nasdaq Basic, while customers accessing the product must comply with applicable licensing, approval and usage requirements.
Pyth’s Data Marketplace provides a new technical distribution channel. Instead of a traditional financial-data vendor delivering the feed only through conventional market-data infrastructure, Pyth can make licensed data easier to integrate into modern software environments and blockchain-linked applications.
This is an important difference from many crypto oracle feeds, where price data is designed for broad public consumption directly onchain. Traditional securities data is governed by contractual rights and exchange rules. Moving the distribution technology closer to blockchain does not automatically remove those legal restrictions.
The relationship therefore demonstrates how traditional market infrastructure may enter onchain finance without abandoning the commercial and regulatory framework that governs the underlying data.
Why Does Nasdaq Require Licensing and Approval?
Market data is itself a commercial product. Exchanges invest in matching systems, market infrastructure and data distribution, then license the resulting information to brokers, banks, trading firms, media companies and other users. How the data is displayed, redistributed or used in automated systems can determine which fees and contractual requirements apply.
For blockchain applications, this creates an important tension. Public blockchains are designed around broad data accessibility, while traditional exchange data frequently comes with restrictions on redistribution. A protocol may be technically able to publish information globally, but that does not mean it has the legal right to do so without authorization.
Pyth’s external-distributor status provides a formal path through that problem. It creates infrastructure through which approved users can obtain the information while Nasdaq retains control over commercial licensing. That may prove more important for institutional adoption than simply placing exchange data into an unrestricted smart contract.
Why Does Onchain Finance Need Licensed Equity Data?
Tokenized Stocks Need More Than Tokenized Ownership
A tokenized stock may represent genuine economic or ownership rights, but the token itself does not automatically know the correct market value of the underlying security. If a tokenized Apple share trades on an onchain venue with limited liquidity, relying only on the local pool price could expose users to manipulation or large valuation errors.
External equity data provides a reference point. Real-time quotes and trades from established securities markets can inform pricing, risk limits and settlement processes. This becomes especially important as the SEC experiments with tokenized NMS stock trading and permissioned onchain liquidity structures.
The emerging market stack therefore has at least two separate requirements. The first is legally valid digital ownership or exposure. The second is reliable information connecting that digital instrument to the underlying market.
Without the second layer, tokenization may improve transferability while weakening price integrity.
Equity Perpetuals and Lending Markets Need Reliable Reference Prices
The requirement becomes even more important for derivatives and lending. An equity perpetual contract needs a reference price to calculate funding, unrealized gains and liquidations. A lending protocol accepting tokenized equities as collateral needs reliable valuation data to determine borrowing limits and identify when positions become unsafe.
Poor data can translate directly into financial losses. If an oracle temporarily reports an incorrect stock price, a borrower could be liquidated unnecessarily or a leveraged trader could receive an incorrect margin calculation. In low-liquidity markets, using only an onchain trading pool as the price source can also create opportunities for manipulation.
Nasdaq real-time stock data can therefore support a broader institutional risk layer. The value of the feed is not merely displaying stock quotes inside a blockchain app; it is providing regulated financial applications with information sufficiently robust to support pricing decisions.
Nasdaq Real-Time Stock Data vs Crypto Oracle Data
Traditional Securities Data Has a Different Economic Model
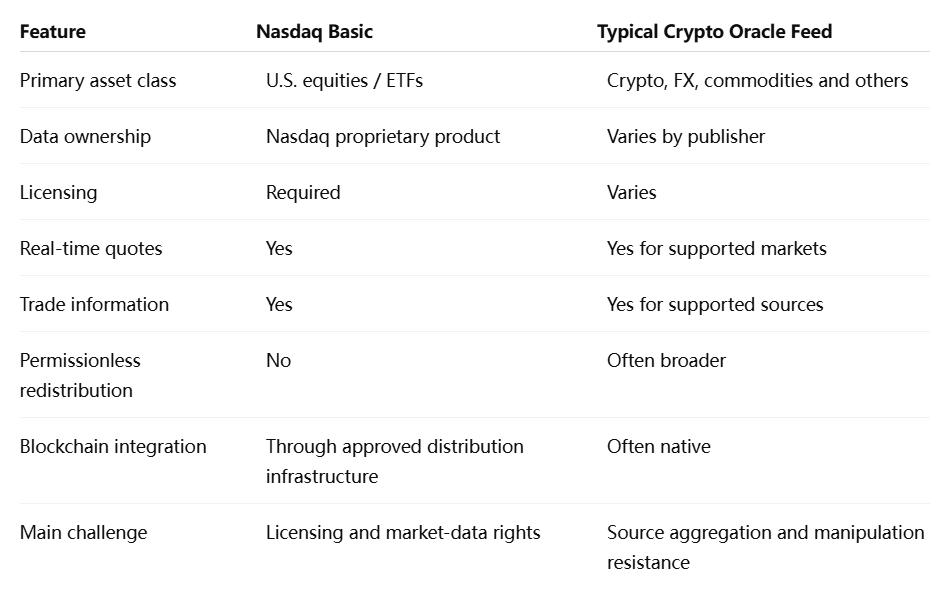
Crypto oracle systems evolved in an environment where exchange prices could often be collected from multiple digital-asset venues and redistributed broadly. Traditional equity markets have a more formalized market-data business with exchange ownership, user classifications and distribution agreements.
As a result, bringing securities data into onchain finance is not simply an engineering project. It requires contractual and regulatory compatibility with the institutions that own the data.
Pyth’s relationship with Nasdaq shows one possible model: preserve the exchange’s commercial rights while modernizing how approved users receive and integrate the feed.
Could Licensed Data Become a Competitive Advantage?
Potentially. As more tokenized securities and real-world asset products emerge, protocols may differentiate themselves not only through liquidity or transaction speed but also through the quality and legal status of their underlying market data.
A protocol referencing a regulated equity may be more attractive to institutions if its valuation process relies on approved exchange information rather than an opaque or unlicensed feed. That could make data provenance an increasingly important part of institutional DeFi due diligence.
The challenge is cost. Licensed professional market data is not free, and protocols must determine how those costs are passed to users or incorporated into business models. The most open blockchain architecture is not necessarily the cheapest once regulated financial data becomes part of the stack.
Why Does This Matter for Tokenized Stocks?
Securities Infrastructure Is Moving Onchain Layer by Layer
The Pyth development becomes more significant when viewed alongside recent changes elsewhere in U.S. market structure. The SEC has begun allowing limited experiments with tokenized NMS stock trading, while trading platforms are exploring equity-linked perpetual products and institutions are expanding tokenized securities infrastructure.
Those developments create demand for a parallel data layer. Putting stocks onchain without bringing reliable price information closer to the same infrastructure would leave a critical dependency outside the system.
The transition is therefore likely to happen in layers. First comes asset representation. Then trading infrastructure develops. Next, pricing, risk, settlement and compliance services need compatible data interfaces.
Pyth becoming an external Nasdaq Basic distributor fits into that progression because market data is one of the foundational components required for the other layers to function reliably.
Does This Mean Nasdaq Is Endorsing Tokenized Stocks?
No. Nasdaq approving Pyth as an external data distributor should not be interpreted as an endorsement of a particular tokenized-equity platform or blockchain financial product.
The relationship concerns market-data distribution. Pyth gains the ability to offer Nasdaq Basic through its marketplace to approved customers, while Nasdaq gains another channel through which its data can reach modern financial applications.
The broader onchain implications come from how developers and financial institutions may use that licensed data, not from Nasdaq explicitly committing to tokenized stock trading.
Maintaining this distinction is important because market-data distribution and securities-product approval are separate functions.
What Are the Main Limits?
Nasdaq Basic Is Not a Complete Replacement for Consolidated Market Data
One limitation is the scope of the feed. Nasdaq Basic can provide broad real-time U.S. equity information, but it is not equivalent to owning every source of market data available across the National Market System.
Institutional trading strategies may require deeper order-book information, multiple venue feeds or consolidated data products. A blockchain application using Nasdaq Basic therefore still needs to decide whether the product contains enough information for its specific use case.
This matters most for applications where precise execution or liquidation decisions depend on the difference between venues. A general price reference may be sufficient for one product but inadequate for another.
Market Hours Still Matter Even if the Blockchain Never Closes
Another limitation is that U.S. stocks do not trade in the same continuous way as crypto assets. A blockchain application can remain active around the clock, but the underlying equity market has defined trading sessions and periods of reduced liquidity.
That creates an important oracle problem. When primary equity markets are closed, the latest official market data may become stale even though an onchain derivative continues moving. Applications need rules for how to handle those periods rather than assuming real-time data exists simply because the blockchain remains online.
Licensing restrictions add another layer. Market data may be technically deliverable to smart contracts but still subject to usage and redistribution limits. Successful institutional products will need architecture that respects both the technical requirements of blockchains and the legal rights attached to traditional market information.
MEXC View: Market Data Is Becoming Onchain Infrastructure
Tokenization cannot scale through asset issuance alone. Every serious financial market depends on pricing, reference data and risk systems, and those functions become more important when leverage or collateral is involved. As equities and other traditional assets move into blockchain-based environments, licensed market data is becoming part of the same infrastructure transition.
For crypto-native markets, this marks a shift from building independent price systems toward connecting directly with established financial-data providers. The distinction matters because institutional users need confidence not only that the price is technically available, but that the data can be used legally and reliably inside regulated products.
The most important metric to watch is therefore not simply how many Nasdaq symbols become accessible through Pyth. It is whether real financial applications begin using licensed exchange data for collateral valuation, derivatives pricing and settlement. If that happens, oracle infrastructure could become one of the most important bridges between traditional securities markets and onchain finance.
Nasdaq Real-Time Stock Data Is Following Finance Onchain
Pyth becoming an external distributor of Nasdaq Basic illustrates a less visible but increasingly important part of financial tokenization. The industry has spent years focusing on moving assets onto blockchains, yet assets cannot support mature capital markets without equally reliable pricing and market information.
Nasdaq real-time stock data gives eligible Pyth customers a licensed source of U.S. equity quotes and trades through an infrastructure designed for modern software environments. The arrangement does not make Nasdaq data freely permissionless, nor does it transform Nasdaq Basic into the full consolidated U.S. equity tape. Instead, it creates a regulated distribution bridge between traditional market data and blockchain-oriented applications.
That bridge could become increasingly valuable as tokenized stocks, equity-linked perpetuals and collateralized lending move onchain. These products require credible prices for funding, margin, liquidations and settlement, and institutional users are unlikely to rely solely on thin onchain liquidity when established exchange data is available.
The larger trend is therefore straightforward: as traditional financial assets move onchain, their supporting infrastructure must follow. Market data, risk management and settlement may ultimately matter as much as token issuance itself. Pyth’s Nasdaq relationship is an early indication that this second layer of tokenization is beginning to take shape.
Sources
https://www.pyth.network/blog/pyth-external-distributor-of-nasdaq-basic
https://www.nasdaq.com/products/data/equities/nasdaq-basic
https://www.pyth.network/data-marketplace
Risk Disclaimer: This article is for reference only and does not constitute investment advice. The cryptocurrency market is highly volatile. Please make decisions cautiously based on your individual circumstances.
You May Also Like
Apple FY2026 Q3 Earnings Date: Report Time, Services Revenue, and iPhone Watchlist
Tokenized Stock Trading: How the SEC's 5-Year Trial Works